
 By Siti Muinah
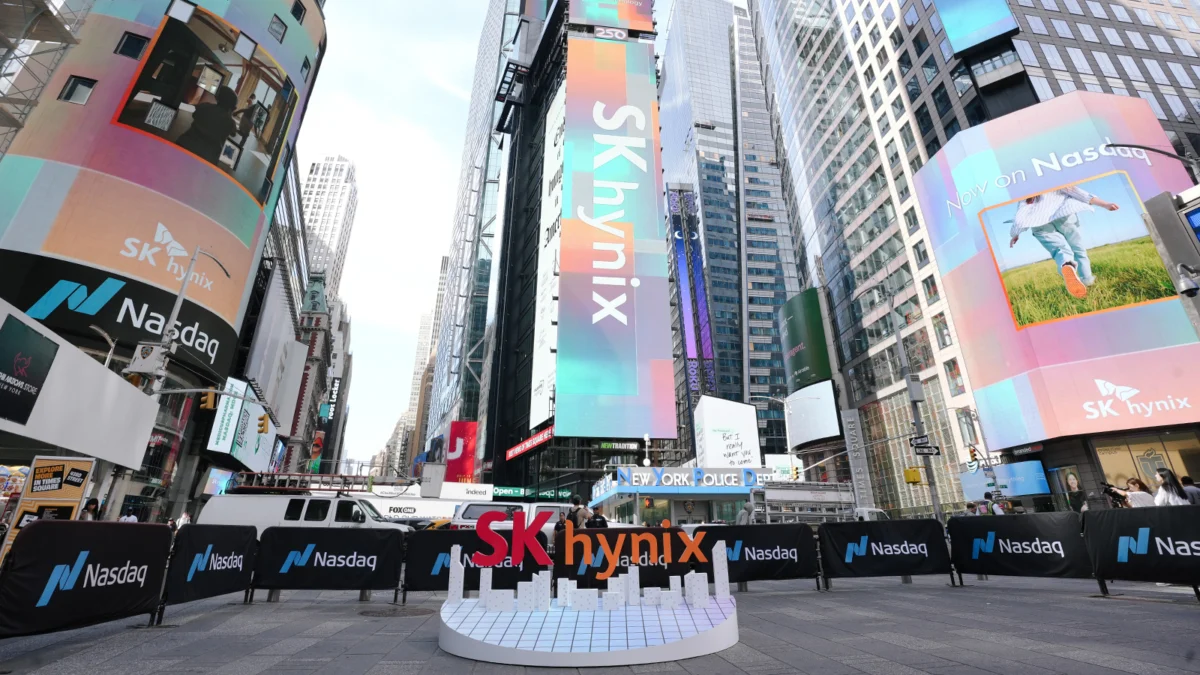
In a move that signals a profound shift in the global semiconductor landscape, South Korean memory giant SK Hynix is currently engaged in high-level discussions with American chipmaker Intel regarding a potential manufacturing partnership. This prospective deal, which would see the Korean titan producing RAM chips on U.S. soil for the first time, underscores the accelerating "onshoring" trend currently reshaping the global electronics supply chain.
As the demand for high-bandwidth memory (HBM)—the lifeblood of modern artificial intelligence—continues to outpace global supply, the strategic necessity of a domestic U.S. footprint has become undeniable. While both parties remain tight-lipped regarding the specifics, the mere prospect of this collaboration reflects a broader realignment of national security interests and corporate strategy.
The Potential Scope: A New Era of U.S. Memory Production
The discussions, first reported by Reuters, revolve around a complex, multi-faceted integration of resources. Industry insiders suggest that one primary model under consideration involves SK Hynix leasing significant cleanroom space at Intel’s ambitious, multi-billion-dollar manufacturing complex in Ohio. By embedding itself within Intel’s U.S. ecosystem, SK Hynix could theoretically bypass the logistical and geopolitical bottlenecks associated with purely overseas production.
Another, perhaps more transformative, model being floated is the creation of a sophisticated joint venture. Such an entity would not be limited to the two chipmakers alone; it could potentially include major cloud-service providers—the primary customers for AI-ready hardware. By involving the "hyperscalers" (like AWS, Microsoft, or Google) directly in the manufacturing loop, the companies could ensure a guaranteed pipeline for memory chips, effectively de-risking the enormous capital expenditure required for modern fabrication plants, or "fabs."
Chronology of a Growing Alliance
The current discussions are not occurring in a vacuum but represent the latest chapter in a long-standing industrial relationship between the two companies:
- October 2020: The foundation of the current trust was laid when Intel sold its NAND flash-memory business to SK Hynix for $9 billion. This acquisition, which eventually formed the basis for Solidigm, signaled a clear division of labor: Intel would pivot toward logic and advanced processing, while SK Hynix would aggressively expand its dominance in the memory sector.
- January 2026: The Trump administration signaled a shift in trade policy, hinting at broader tariffs on semiconductor imports while offering significant tax and tariff relief for companies willing to commit to domestic manufacturing. This policy environment created the economic "push" factor for the current talks.
- July 2026: SK Group Chairman Chey Tae-won publicly voiced support for diversifying the company’s manufacturing base, stating that building factories in the U.S. is a strategic necessity if the economics prove feasible. During the same month, SK Hynix successfully listed American depository receipts on the Nasdaq, deepening its integration into U.S. capital markets.
- September 2026: Reports emerge detailing active negotiations between SK Hynix and Intel, moving the concept of domestic RAM production from a theoretical ambition to a potential operational reality.
Supporting Data: The AI Memory Boom
The urgency behind these talks is fueled by a singular force: the insatiable appetite for High-Bandwidth Memory (HBM). Unlike traditional DRAM, which is used for general computing, HBM is essential for the graphical processing units (GPUs) that power Large Language Models (LLMs) and generative AI.
SK Hynix has been the primary beneficiary of this trend. Recent earnings reports have shown record-breaking revenue growth, driven almost exclusively by its HBM3 and HBM3E product lines. To sustain this lead, the company is already committed to a $3.8 billion advanced packaging and research facility in West Lafayette, Indiana. Set to begin production in 2029, this facility represents a "bridgehead" for the company. While the Indiana plant will focus on packaging—the process of assembling and testing chips—the potential Ohio collaboration would represent a move further up the value chain: the actual fabrication of the memory wafers themselves.
Official Responses and Corporate Caution
Despite the gravity of the potential deal, both companies are maintaining a posture of careful diplomacy. In a statement provided to TechCrunch, an SK Hynix spokesperson emphasized that the company is constantly evaluating its global footprint to ensure competitiveness, yet stopped short of confirming any firm plans.
"SK Hynix is exploring various options to strengthen its global competitiveness, but no specific plans or arrangements have been finalized at this time," the statement read. "No decisions have been made regarding the two scenarios mentioned in the report."
Intel, similarly, has opted for silence, declining to comment on the speculation outside of regular business hours. This silence is typical of the semiconductor industry, where multi-billion-dollar deals are often subject to complex regulatory, labor, and technical negotiations that can span years before a formal announcement is made.
Strategic Implications and Challenges
The Geopolitical Tightrope
For SK Hynix, this deal is not merely a commercial decision; it is a geopolitical balancing act. The South Korean government keeps a watchful eye on its domestic "semiconductor champions." Any transfer of cutting-edge chip technology to U.S. facilities could trigger a review under the Korean government’s technology protection laws. Seoul remains cautious about the potential "hollowing out" of its domestic tech sector, even as it acknowledges the necessity of staying in the good graces of its primary security ally, the United States.
The Domestic Manufacturing Hurdles
The U.S. manufacturing environment presents its own set of challenges. Critics of the current "chip-nationalism" trend often point to the high cost of labor, regulatory complexity, and the scarcity of specialized talent in the American Midwest. However, the prospect of an Intel-SK Hynix partnership could alleviate some of these concerns. By leveraging Intel’s existing infrastructure and institutional knowledge in Ohio, SK Hynix could potentially accelerate its "time-to-market" for U.S.-made chips, bypassing the years of site preparation usually required for greenfield projects.
The Role of the Hyperscalers
Perhaps the most intriguing aspect of the proposed joint venture is the potential inclusion of cloud-service providers. For years, companies like Amazon, Microsoft, and Meta have been vertically integrating their hardware stacks to gain better control over performance and costs. If these companies invest directly into a shared manufacturing facility, it would represent a fundamental change in the industry structure. Instead of a "merchant market" where chipmakers sell to anyone, we could see the emergence of "dedicated supply chains" where the customers own a slice of the factory floor.
Conclusion: The Path Forward
The potential marriage of SK Hynix’s memory expertise and Intel’s U.S. manufacturing infrastructure marks a turning point in the global tech war. As the world moves toward a future defined by artificial intelligence, memory has transitioned from a commodity to a strategic asset.
While no final ink has been put to paper, the trajectory is clear: the era of centralized, Asia-only chip production is ending. Whether this deal manifests as a lease agreement, a joint venture, or a new model of collaborative fabrication, it signals that the geography of the semiconductor industry is being redrawn by the twin forces of AI demand and national security. For now, the global tech sector waits to see if this marriage of convenience will become the foundation of a new American silicon corridor.
 Neng Nana
 Laily UPN
 Ammar Sabilarrohman
